What Should I Ask a Lender Before I Borrow Against My Rolex?
A Rolex can be more than a watch when a small business hits a cash-flow gap. A business owner might need to cover payroll before a customer pays an invoice, buy inventory ahead of a busy season, or handle an unexpected repair. Borrowing against a watch may provide another option—but the tempe ecommerce inventory funding lender’s offer is only as useful as its terms, timeline, and consequences if repayment goes wrong.
Before handing over your watch, ask how the lender values it, what you will actually receive, when repayment is due, and exactly what happens on default. Also check whether the loan adds a personal guarantee or other obligations beyond the watch itself. These questions help you compare a collateral-based loan with a bank line of credit, an SBA loan, or another source of working capital.
Start with the repayment plan, not the watch’s headline value
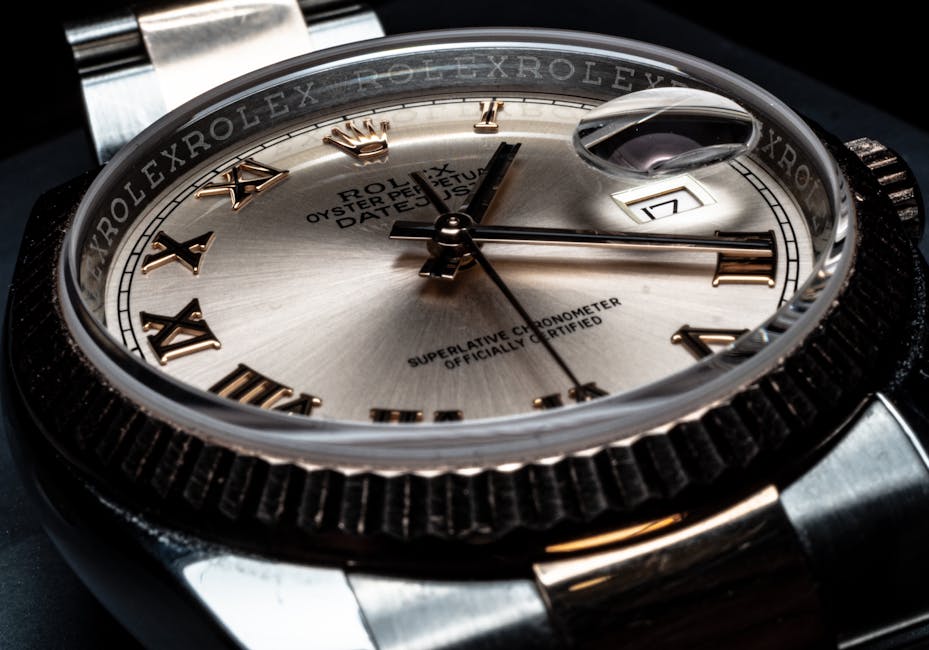
Secondary-market prices can help you understand what buyers are paying for similar Rolex models, but a public asking price is not a lender’s guaranteed valuation—or the amount you will receive. The condition, reference, age, dial, box and papers, service history, and current demand can all affect the offer. A lender may also account for the cost and risk of selling the watch if you do not repay.
Use publicly tracked secondary-market pricing data as a starting point. Compare watches with the same reference and similar condition, and distinguish completed sales from listings where the seller has not found a buyer. Then ask the lender to explain its own valuation and show how it arrived at the amount it is willing to advance.
What it means for payroll: The loan amount that matters is the cash you can use after fees—not the market value you saw online or the lender’s estimate of the watch.
Questions about valuation and authentication
Ask who inspects the watch and what qualifications that person has. A lender should be able to explain its authentication process, including how it checks the watch’s components and condition. If the lender relies on an outside evaluator, ask who the specialist is and whether you can receive a written report.
- Who authenticates the watch? Ask for a qualified specialist with relevant Rolex experience, not simply a general intake employee.
- What does the inspection cover? Clarify whether the specialist examines the movement, case, dial, bracelet, serial and reference details, and any replacement or aftermarket parts.
- Will I receive the valuation in writing? Ask for the model details, condition grade, valuation basis, and any deductions.
- How do box, papers, service records, and accessories affect the offer? Ask whether missing items lower the advance and by how much.
- Can I decline after the inspection? Find out whether you owe an appraisal, storage, or other fee if you decide not to proceed.
- How will you store and insure the watch? Ask where it will be held, who can access it, what insurance covers, and who bears responsibility for a loss or damage.
Authentication matters to both parties: it helps the lender assess the collateral and helps you understand what you are pledging. Keep copies of the watch’s photographs, documents, service records, and the signed intake receipt. Do not rely on a verbal assurance about insurance or storage; ask to see the relevant contract language.
Understand how a collateral-based loan works
In a collateral-based loan, the lender takes possession of—or otherwise establishes a security interest in—an asset to support repayment. With a pawn-style arrangement, the lender typically holds the watch during the loan. Other structures may differ, so ask what legal arrangement the lender is using and what rights each party has.
Loan-to-value (LTV) is the loan amount compared with the lender’s assessed value of the collateral. What it means for payroll: A lower LTV can mean you receive less cash than the watch’s estimated value, so plan around the net advance rather than the appraisal.
Ask how the lender calculates LTV and whether it can change after inspection. Check whether you can borrow more later, whether the lender can demand additional collateral, and whether it can revalue the watch during the term. Do not assume that the watch’s public resale value equals the amount of debt it secures.
Ask direct loan term questions
Get every material term in writing before you sign or leave the watch. Compare the total cost of the loan—not just the stated interest rate. Fees, payment frequency, extension charges, and the way interest accrues can change what you owe.
Ask the lender Why the answer matters What is the amount I will receive after all fees? Shows the usable cash, rather than the gross loan amount. What interest rate applies, and is it stated monthly or annually? Lets you compare offers using the same period and basis. What fees apply at origination, during the term, or at payoff? Reveals charges that may not appear in the advertised rate. Does interest compound, and how do you calculate the payoff amount? Clarifies how the balance grows and what you must pay to reclaim the watch. Can I repay early without a penalty? Matters if a customer pays an invoice sooner than expected. Can I extend or renew the loan? What will that cost? Shows whether an extension is available—and whether it increases the total cost. Is there a grace period, and what happens if I miss a payment or deadline? Identifies the point at which fees, default, or loss of the watch may follow. Do I have to make regular payments, or is the full balance due at maturity? Distinguishes an installment schedule from a lump-sum repayment obligation.Annual percentage rate (APR) expresses borrowing cost over a year, though the calculation and required disclosures can depend on the product and lender. What it means for payroll: Compare the APR and total dollars due with the cash you expect to have available on each payment date.
Ask the lender to provide a payoff example for the date you expect to repay, including every fee. If the lender will not show a clear calculation, treat that as a reason to pause.
Pin down the repayment timeline
A short-term loan can fit a short-term cash-flow gap only if the repayment date matches a dependable source of cash. Map the loan’s due dates against payroll, rent, tax payments, vendor bills, and expected customer receipts. Do not base the plan on an invoice that has not been approved or a sale that may not close on time.
Ask these repayment timeline questions:
- When does the term begin: on approval, funding, or the day you hand over the watch?
- What is the exact maturity date, and what time zone or cutoff applies to payment?
- How long does a bank transfer or other payment method take to post?
- When can I collect the watch after I repay, and what identification or paperwork will I need?
- If a customer pays late, can I extend the term before the due date? What does the extension cost?
Repayment timeline means the schedule from funding through final payoff, including any processing time to release your collateral. What it means for payroll: Make sure the money will arrive before payroll is due—and that the lender will release the watch when you have completed the required payoff.
Ask what happens on default
“Default” can mean more than missing the final payoff date. The contract may define default to include a missed payment, failure to pay an extension fee, or another breach. Ask the lender to identify each trigger, the notice it will give you, and the time you have to fix the problem.
Then ask the most important question plainly: What happens on default? Does the lender take ownership of the watch, sell it, or follow another process? If it sells the watch, how does the contract handle sale proceeds that exceed the debt and costs? Could you still owe a deficiency if the proceeds do not cover what you owe? The answer depends on the contract and applicable law, so read the actual documents and consider getting legal advice if any clause is unclear.
Ask whether you can retrieve the watch after the deadline by paying the balance and fees, and whether the lender must send notice before selling it. Get the deadlines and notice method in writing. Never assume that surrendering the watch automatically settles every possible obligation.
Check for a personal guarantee
A loan secured by a Rolex does not automatically tell you whether the lender can pursue you personally for unpaid amounts. Ask directly: Does this agreement include a personal guarantee? Also ask whether you are signing in your individual capacity, whether a spouse or co-owner must sign, and whether any business assets or other collateral secure the debt.
Personal guarantee means an individual may be responsible for a business debt under the agreement. What it means for payroll: If the business cannot repay, a guarantee could put personal finances beyond the pledged watch at risk, depending on the contract and law.
Read the promissory note, collateral agreement, and any guarantee together. If a salesperson says the watch is the lender’s only recourse, confirm that statement in the contract before signing.
Compare speed with cost
A collateral loan may involve fewer steps than some bank or SBA financing processes because the lender can focus heavily on the pledged asset. But do not accept “fast approval” without a defined timeline. Ask how long inspection, underwriting, funding, and watch release each take, and whether the lender commits to those timings.
A bank line of credit may offer a better fit for recurring working-capital needs, but the application can require financial statements, tax returns, and a review of business credit. SBA-backed financing may suit a longer-term business need, https://instaquoteapp.com/can-i-borrow-against-a-watch-collection-or-just-one-rolex/ but it has eligibility and documentation requirements and is not necessarily a quick fix for a near-term payroll gap. Compare actual offers and timelines rather than assuming one product is always cheaper or faster.
Working capital is money available to cover routine business expenses and timing gaps. What it means for payroll: Choose financing whose payment schedule fits the dates your business collects cash, not just the date the lender can fund it.
Use a short pre-signing checklist
- Get a written valuation and have the watch reviewed by a qualified authentication specialist.
- Compare the valuation with publicly tracked secondary-market pricing for genuinely similar watches, while separating asking prices from completed sales.
- Confirm the net amount you will receive, the full cost, payment dates, maturity date, and early-payoff terms.
- Build a repayment plan around a reliable source of business cash, with a backup if that payment is delayed.
- Read the default, sale, notice, and personal-guarantee provisions before signing.
- Get written terms for storage, insurance, and return of the watch after payoff.
Bottom line
Borrowing against a Rolex can bridge a temporary business cash-flow gap, but it puts a valuable, saleable asset at risk and may cost more than other financing. Ask the lender to explain its valuation, authentication, fees, repayment timeline, and default process in plain language. Confirm whether you have a personal guarantee, and do not sign until the contract matches what the lender told you.
If the repayment depends on a customer paying “soon,” make a backup plan before pledging the watch. The best financing decision is not simply the one that puts cash in your account first; it is the one your business can repay on time without creating a larger problem.